Mobile Payment Apps: A Safe 2026 Spending Guide
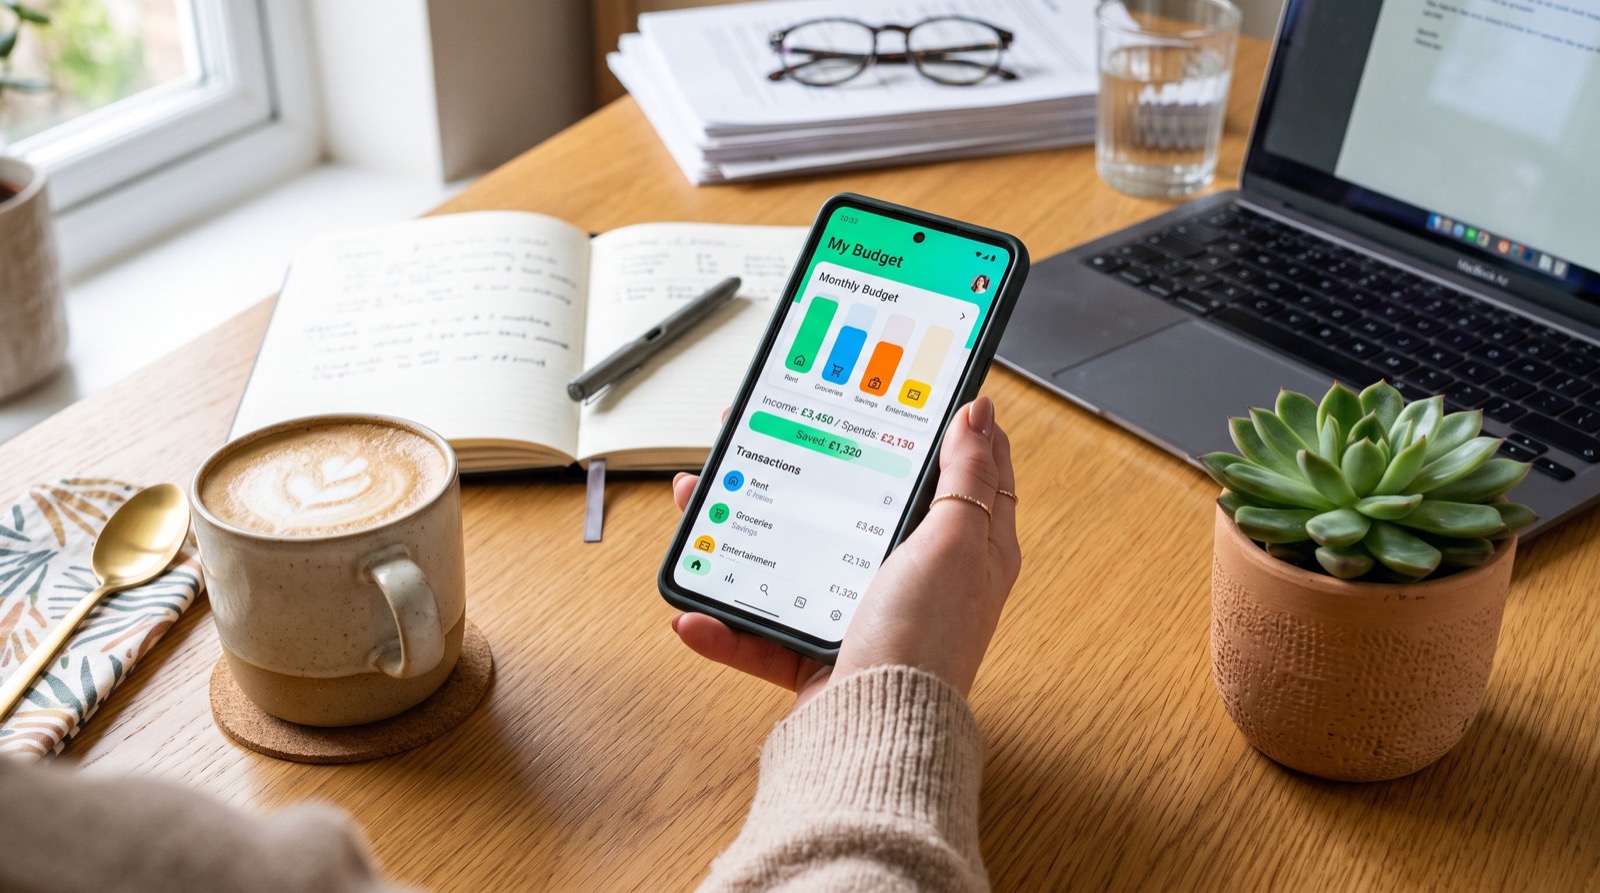
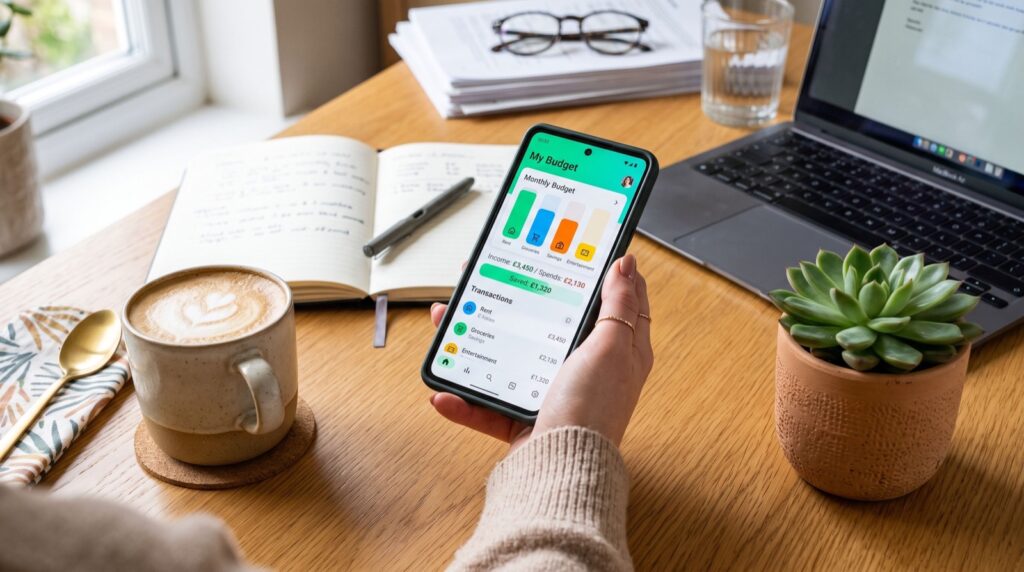
Mobile payment apps now sit between you and nearly every purchase, from the morning coffee to the rent. In 2026, tapping a phone or sending a few taps of cash to a friend feels so ordinary that most people never stop to think about what happens behind the screen. That convenience is a gift, but it also hides fees, privacy choices, and fraud risks that quietly shape your finances. This guide explains how mobile payment apps work, where the money actually goes, and how to use them without getting burned.
I switched to a phone-first wallet years ago and rarely carry cash now. The upsides are real, and so are the lessons I learned the hard way.
How Mobile Payment Apps Actually Move Your Money
Under the hood, most mobile payment apps fall into two buckets. Tap-to-pay wallets store a tokenized version of your card and relay it to the register. Peer-to-peer wallets hold a cash balance and shuttle it between users.
The distinction matters because the protections differ. A tokenized card payment usually inherits your card’s fraud coverage, while a P2P transfer from a stored balance often does not. Knowing which type you are using tells you how much safety net sits behind each tap.
Tap-to-pay versus peer-to-peer
| Feature | Tap-to-pay wallet | P2P wallet |
|---|---|---|
| Links to | Your card | Stored balance or bank |
| Fraud coverage | Usually strong | Often limited |
| Reversible | Often, via card dispute | Rarely |
| Best use | Retail checkout | Paying friends |
Staying Safe With Mobile Payment Apps
Security with mobile payment apps comes down to a handful of settings you configure once. Most fraud succeeds not through clever hacking but through social pressure and rushed taps. Slow down and the risk drops sharply.
- Lock every payment app behind biometrics or a passcode.
- Turn on transaction alerts so you catch odd charges instantly.
- Only send P2P money to people you personally know.
- Ignore “pay now or lose it” pressure; that urgency is the scam.
The Federal Trade Commission tracks the fastest-growing payment scams and publishes free, practical warnings. Skim the FTC guidance on payment app scams before you send money to anyone you have not met.
A habit that stops most P2P fraud
Send a tiny test amount, like one dollar, before any large transfer to a new recipient. Confirm they received the right amount, then send the rest. This ten-second step has saved me from two mistyped usernames and one lookalike account.
What Do Mobile Payment Apps Really Cost?
Most everyday use is free, but a few features carry charges that stack up over a year. Instant transfers to your bank, credit-card-funded sends, and out-of-network ATM withdrawals are the usual fee traps. The apps rarely hide these, yet few users ever read the schedule.
- Default to standard-speed transfers, which are almost always free.
- Fund sends from a linked bank, not a credit card, to dodge surcharges.
- Withdraw cash only from in-network ATMs.
- Review your monthly statement for fees you forgot you agreed to.
Smart spending habits amplify those savings. These down-to-earth personal finance tips pair well with any wallet you choose and keep the small leaks from draining your budget.
Building a Simple, Safe Payment Stack
You do not need a wallet for every occasion. One tap-to-pay wallet for retail and one trusted P2P wallet for friends covers almost everyone. Keeping the stack small makes it easier to monitor and harder for charges to slip past you.
When you compare options, look past the sign-up bonus and judge the fraud policy, the fee page, and how quickly support answers. A broad look at today’s money apps helps you weigh those traits side by side before committing.
- Pick one retail wallet and one P2P wallet.
- Link them to accounts you check at least weekly.
- Set a monthly reminder to review connected apps and permissions.
If you want help wiring up the broader digital side of your finances, our reliable local experts explain related online tools without the jargon.
Privacy Settings Most People Never Touch
Mobile payment apps ship with default settings tuned for the company, not for you. Many P2P wallets, for instance, make your transactions public by default, so strangers can scroll your payment history. A two-minute trip into settings closes that window for good.
Privacy is not just about hiding embarrassing purchases. Public transaction feeds reveal patterns that help scammers craft convincing messages, and they leak social details you never meant to share. Locking things down shrinks your attack surface without costing you a single feature.
Settings to change on day one
- Set transactions to private so your activity never appears in a public feed.
- Disable contact syncing if you do not need to find friends by phone number.
- Turn off promotional data sharing in the privacy menu.
- Require confirmation for any transfer above a threshold you set.
Beyond the app itself, your phone’s own protections form the outer wall. Keep the operating system updated, since security patches close the holes scammers exploit, and never approve a payment because someone rushed you on a call. Legitimate businesses do not demand instant P2P transfers.
Think about recovery before you ever need it in 2026. Note the in-app path to report fraud and the support contact, and store a backup payment method elsewhere. When something goes wrong, calm preparation beats frantic searching while your money sits frozen.
I once caught a lookalike account only because confirmations were switched on, giving me a final chance to read the username. That extra tap felt mildly annoying for months, then saved a meaningful transfer in a single second. Small friction, large payoff.
Frequently Asked Questions
Are mobile payment apps safe for everyday purchases?
Tap-to-pay wallets are very safe because they tokenize your card and inherit its fraud protection. Lock the app with biometrics and enable alerts, and daily use carries little risk.
Can I get my money back after a P2P transfer?
Usually not, since most peer-to-peer transfers are final. That is why you should only send to people you know and always confirm the recipient first with a small test amount.
Do mobile payment apps charge fees?
Standard transfers are typically free, but instant cash-outs, credit-card funding, and out-of-network ATMs cost extra. Choose default settings and read the fee page to avoid surprises.
How many payment apps should I use in 2026?
Two is plenty for most people: one tap-to-pay wallet for stores and one P2P wallet for friends. A small stack is easier to secure and monitor.
Spend Smarter Starting Today
Mobile payment apps make a cashless life effortless, but the convenience only pays off when you control the fees and lock down the fraud risks. Keep your stack small, default to free transfers, verify every new recipient, and read the alerts your app sends. Set up those safeguards today, and your phone becomes a tool that protects your money instead of quietly draining it.